Vol Lab and 0DTE Lab
The volatility and 0DTE panels on the options, with directional bias, IV and skew, implied against realized volatility, pin and exposure by strike.
Beyond the flow, a few panels dig into volatility and into the day’s 0DTE positioning. They are in the Workspace library under Options & GEX and read the same chain as the other options panels: the CME options on ES and NQ, or QQQ and SPY on Desk (see GEX and the flip point). Desk is coming soon: the waitlist is on the pricing page.
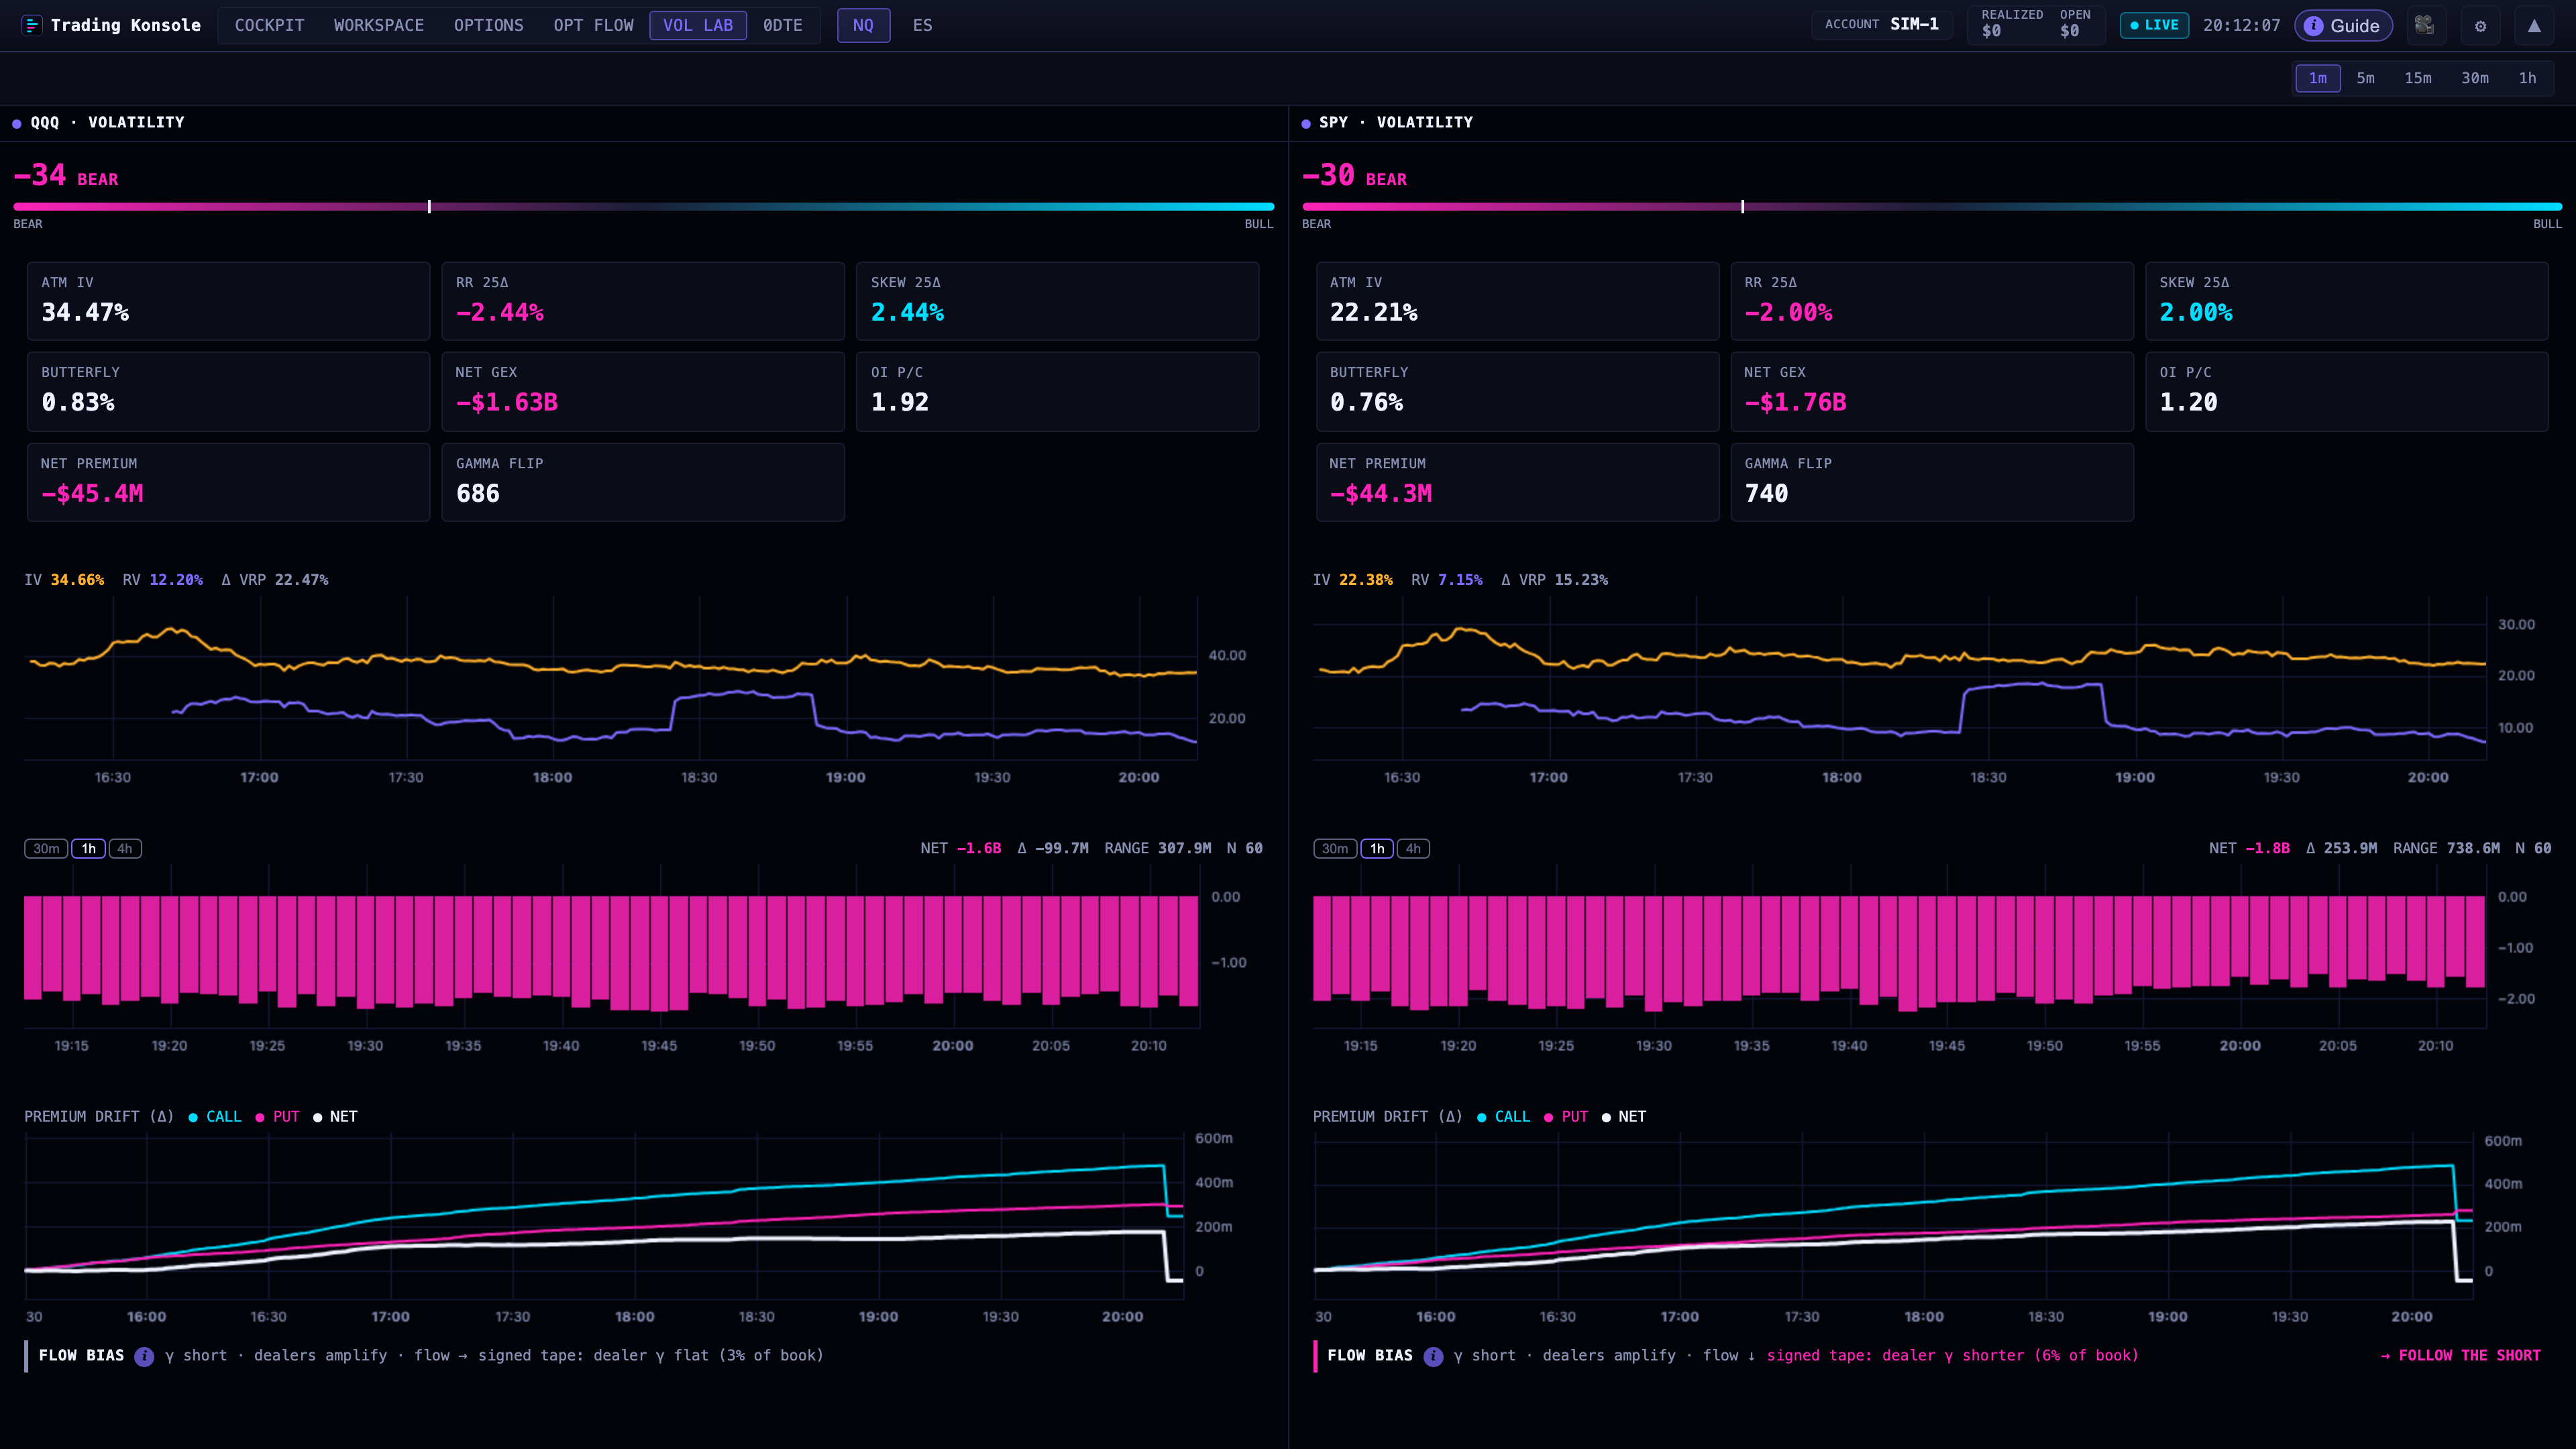
Vol Lab
The directional bias of the day’s options (risk reversal, premiums, GEX), with implied volatility, skew and butterfly for each underlying.
IV vs Realized and IV %
- IV vs Realized, ATM implied volatility against realized volatility over time, with the spread between the two (VRP).
- IV %, the session’s ATM implied volatility as a sub-chart.
0DTE Lab
Pin, vanna and charm, and the Gamma, Vanna and Charm exposure by strike for the day’s expiry. On the CME source that is the front expiry: ES and NQ have options expiring every day.
History
On the CME source the history starts from when the app is running: the curves over time begin at that point.